Any other business

Why Switzerland should have listened to Hong Kong on currency pegs

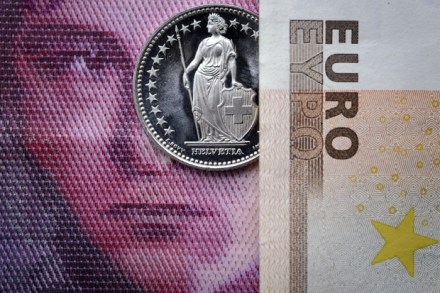
The Swiss National Bank usually ticks away as quietly as one of its nation’s more expensive timepieces, but when the cuckoo does occasionally burst out of the clock, all hell breaks loose. After a policy was introduced in September 2011 to depress the Swiss franc against the euro (as traumatised investors continued to pour money into safe-haven Switzerland), governor Philipp Hildebrand resigned when it came to light that his wife Kashya had sold a huge bundle of francs ahead of her husband’s market intervention, then bought them back at a handsome profit. Now, weeks after Hildebrand’s successor Thomas Jordan called the informal fixing of the franc at €1.
The RMT’s Mick Cash and Tesco’s Dave Lewis win my prizes for media manipulation

Mixed results for the Brits at the Golden Globes, but I’m pleased to announce that my Golden Monkey Wrench for media manipulation goes to Mick Cash and his team at the Rail Maritime & Transport union, for securing wall-to-wall sympathetic coverage of the collapse of courier firm City Link — some 2,300 of whose workers learned on Christmas day that their jobs were doomed. It would be fair to say Mick had not made much impact as general secretary of RMT (give or take some pointless Tube strikes) since the death of his mighty predecessor Bob Crow last March, but he certainly grabbed the City Link story by the throat — and has been busy this week urging MPs to investigate ‘the whole murky business’.

The eurozone is strong enough to kick out Greece if Syriza wins

Ever since European Central Bank president Mario Draghi declared himself ready, in July 2012, ‘to do whatever it takes to preserve the euro’, the likely disintegration of the single currency — as predicted by pundits such as yours truly over the preceding years — has all but disappeared from the comment agenda. The combination of a persuasive ECB leader with reform in some bailed-out eurozone states (notably Ireland and Spain) and an easing of bond market pressures, plus the iron will of Germany to see the euro survive, drove the break-up argument into retreat.

What to expect in business in 2015 (probably not the Triumph of Probity, Honour and Prudence)

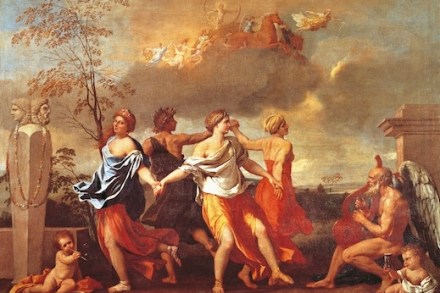
You might recall a column I once wrote about a party at the Wallace Collection. It took place in late 2008, the host was the US investment bank Morgan Stanley, and I compared the assembled financiers — who saw the crisis then raging as just one more opportunity to make money out of volatility in markets that were bound to swing round again — to the circle of dancers in Poussin’s ‘Dance to the Music of Time’, which hangs in the Great Gallery there. Far-fetched perhaps, but I have a weakness for allegories. On a pre-Christmas visit to the Wallace, I found the gallery splendidly refurbished and re-hung. The ‘Dance’ — like the banking sector — is in a different place but still emitting the same signals.

How do I ever get speaking gigs? I’m guessing it goes like this…

To Brighton, to address a conference of property investors. Unusually, I find myself programmed alongside both Gerard Lyons, City economist turned Mayor Boris’s adviser, who is notably upbeat in his forecast, and Robert Peston, who is distinctly downbeat in an extended after-dinner lecture with graphs, but gets away with it because his voice mannerisms are so compelling and women in the audience are fascinated by his new haircut.

Cheap oil has finally arrived – and it looks like being a disaster

This oil price slump is turning into a ‘black swan’: one of those economic events that seem to come from nowhere with strange and unforeseen effects. As Brent Crude dips below $70 a barrel and Opec sits on its hands, major banks face losses on financings for US energy companies that must have looked like the safest borrowers in the field in an earlier phase of the shale gas boom. As the rouble plunges and the Russian economy implodes, anyone holding debt paper issued by a Siberian oil giant or a contract to build an oligarch’s superyacht may end up lighting the fire with it. The only thing that has barely flickered is the price of petrol at the pump, so consumers are feeling scant benefit.

Forget corporate social responsibility: just do a proper job

A theme of this autumn has been conversations about corporate reputation and how it is guarded or lost. To name but three, I have kicked this around at a ‘Trust Forum’ sponsored by the lawyers DLA Piper at Oxford’s Said Business School, at a lunch hosted by the wealth managers McInroy & Wood, and in an interview with Lord (Stuart) Rose, former Marks & Spencer chief, at last week’s York Business Conference. The essence is that most big companies feel their reputations are increasingly fragile, and that public trust is now routinely and unfairly denied to them. Non-banks blame banks for letting the side down. All companies blame the media for failing to report good news, and social media for spreading false or subversive rumours.

Are the Qataris ready for the curse of Canary Wharf?

I’ve written before of a ‘curse of Qatar’ that might explain misfortunes attending the Gulf state’s UK investments, of which the seven-years-delayed Chelsea Barracks redevelopment is an example. I also claim to have coined ‘curse of Canary Wharf’, a phenomenon afflicting not only financial tenants of the Docklands complex but visitors such as Gordon Brown, who never lived down his speech congratulating Lehman Brothers on ‘the contribution you make to the prosperity of Britain’ at the opening of the doomed bank’s office tower there. So the prospect of a renewed Qatari bid for Songbird, the corporate owner of Canary Wharf, fills me with foreboding.

Why I’m glad there’s no British Las Vegas

I didn’t realise that the Rialto Bridge has a moving walkway and muzak, that the gondolas beneath it float on a clear blue pool, and that the school of Tiepolo had so many apprentices available to paint hotel ceilings. ‘Still in Venice, Martin?’ you’re thinking. ‘Surely that was last month?’ Well no, your intrepid columnist has moved from the old world to the new, and reports this week from the desert frontier where unfettered capitalism meets the lowest human urges: Las Vegas. It’s an overwhelming experience, so forgive me if my grip on what’s happening at home — reactions to David Cameron’s CBI conference speech, for example, and the rejected Qatari bid for Canary Wharf — is a little hazy.

What British start-ups are still missing

This issue includes the new Spectator Money supplement, in which I hope you’ll find a bouquet of stimulating ideas. The cover piece by the enterprise campaigner Michael Hayman waxes lyrical on the important theme of investing in high-tech start-ups: important because it’s an exciting thing to do with the slice of savings on which you’re happy to take higher risks, but also because bold new businesses hold the key to future growth. At a dinner hosted by Hayman last week, I met a selection of business founders and early-stage investors. The mood was one of optimism in what’s seen as an increasingly benign UK arena for start-ups, buzzing with world-class ideas and underpinned by programmes such as the Seed Enterprise Investment Scheme.

How Italy failed the stress test (and Emilio Botín didn’t)

Continuing last week’s theme, it was the Italian banks — with nine fails, four still requiring capital injections — that bagged the booby prize in the great EU stress-testing exercise, followed predictably by Greece and Cyprus, while Germany and Austria (with one fail each) fared better than some of us had feared. The most delinquent European bank turned out to be the most ancient, Banca Monte dei Paschi di Siena, which was judged to have a capital shortfall of €2.1 billion as a result of a very modern set of problems. Founded in 1472 as a kind of charitable pawnbroker, the bank which eventually became Italy’s third largest had a more or less blameless 527-year record until it listed on the Italian stock exchange in 1999.

The one economic indicator that never stops rising: meet the Negroni Index

This dispatch comes to you from Venice — where I arrived at sunset on the Orient Express. More of that journey on another occasion, I hope. Suffice to say that if you happen to have been wrestling with the moral choice of bequeathing what’s left of your tax-bitten wealth to ungrateful offspring or spending it on yourself, don’t hesitate to invest in a last fling on this time capsule of elegant extravagance. Made up of rolling stock built in the late 1920s, the train itself symbolises everything that 20th-century Europe was good at — engineering, craftsmanship, style, cross-border connections — when not distracted by political folly and war.

Storm warning: the world economy’s October troubles aren’t over yet

October is always a turbulent month, and I’m feeling uneasy about this one. The FTSE100 index, which looked set to break through 7,000 in September, has lost more than 500 points since then — and would have lost more but for manoeuvres in the mining sector. Pessimism stalks the bond markets, and even a falling oil price is read more as a harbinger of faltering growth than a stimulus for further recovery. Ebola is the new volcanic ash cloud, and attention is focused on the apparently incorrigible weakness of the eurozone — where the biggest problem is what was long seen as the most potent solution, namely the German economy. Fiscal discipline, strict wage control and relentless pursuit of export success made Germany the locomotive of Europe for the single-currency era; but a 0.

Yes, Wonga lent at shocking rates – but it was customers who lied

‘Payday Lady is not trading at this time,’ says her website, sounding a little like La Dame aux camélias. Indeed (since I could not find her anywhere) the message may indicate that Payday Lady is not just temporarily indisposed, but has given up the game altogether. I’ll be glad to hear from her if she hasn’t. Meanwhile I can report that her rival Cash Lady (who promises she’ll be ‘here to help you’ within three minutes) was still out there — despite having her television ads banned last year — and so were Purple Payday, Pounds to Pocket, Peachy Loans, PayDay Pig and CashCowNow, all at colossal ‘representative APRs’ that look relatively cheap compared with Wonga’s notorious 5,853 per cent.

Why the real winner from George Osborne’s ‘Google tax’ could be Nigel Farage

George Osborne’s promise to crack down on multinational companies’ avoidance of UK taxes by the use of impenetrable devices such as the ‘Double Irish’ and the ‘Dutch Sandwich’ certainly has the support of this column. I have long argued that the ‘fiduciary duty’ (identified by Google chairman Eric Schmidt) to minimise tax bills within the law for the benefit of shareholders has to be balanced against a moral duty to pay at least a modicum of tax in every profitable territory.

Is the US using bank fines to bring allies into line against Russia?

Here’s one for all you conspiracy nuts out there, prompted by readers’ comments on my recent item about whether BP has been unjustly targeted by the US political and judicial establishment. I gather there’s a theory that the hounding of non-US banks by the US Department of Justice for sanctions-busting and trading misdemeanours has a more sinister foreign-policy impetus behind it. Notably — according to Conflicts Forum, a website I’m told is breakfast reading for trainee spooks — the $9 billion fine imposed by US authorities on BNP of France for financing trade with Iran, Sudan and Cuba may also have been intended to punish the French for refusing to cancel their contract to build two Mistral-class amphibious assault ships for the Russian navy, about which I wrote in August.

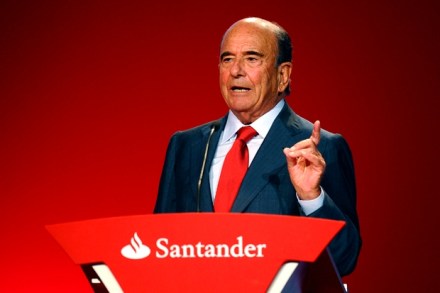
Santander’s secret: to conquer the world, stay like a small-town bank

Four years ago, I wrote that I knew no dark rumours about Santander, the rising force in UK high street banking, but that history taught me banks which expand rapidly and globally ‘always come unstuck in the end… partly because the challenge of risk control across such vast portfolios becomes impossible… Banks that have been driven by one powerful personality also tend to lose management grip, and start finding skeletons in cupboards, as the big man comes to the end of his tenure.’ The big man in question was third-generation chairman Emilio Botín — who died in post last week, aged 79.

BP’s been punished enough – but not because Americans hate the Brits

I should declare two connections before I start offering opinions about the latest US judgment against BP relating to the ‘Macondo’ disaster — the explosion on the Deepwater Horizon oil rig and subsequent spillage in the Gulf of Mexico in 2010. The first is that I’m occasionally invited to interview BP executives for its in-house magazine. That doesn’t mean I’m in their camp, but it does mean I have had the opportunity to discuss Macondo with, among others, chairman Carl-Henrik Svanberg, and I did not think he was merely parroting the corporate line when he told me, ‘We’re not going to let people take advantage of us, but we’re going to do what’s right and be a showcase of responsibility.

Rona Fairhead will be good for the BBC – but who was so keen to nobble her rival?

Hats off to Rona Fairhead, the former Financial Times executive who will succeed Lord Patten as chairman of the BBC Trust. It requires a brave spirit to take on this poisonously politicised role — and Fairhead starts with the disadvantage that everyone thinks they know the roll call of candidates who might have been preferred but declined to apply, including her own former boss Dame Marjorie Scardino, for whose job as head of Pearson, the FT’s parent, Fairhead was passed over last year. But a mole tells me she’s ‘as steely as she’ll need to be’; and leading ladies of the non-executive circuit (she’s on the boards of HSBC and PepsiCo) are also full of praise, though one says: ‘She must like stress.

Europe’s leaders worship Mario Draghi. They should listen to him instead

European Central Bank President Mario Draghi secured a place in history by his demonstration, on 26 July 2012, of the power of words in a financial crisis. Not long in office, he had already shown willingness to act firmly, averting a liquidity crunch by providing three-year lending facilities for European banks. That day, he told a conference in London: ‘Within our mandate, the ECB is ready to do whatever it takes to preserve the euro. And believe me, it will be enough.’ While the rest of the speech was an opaque metaphor about the euro as a bumblebee — ‘a mystery of nature because it shouldn’t fly but instead it does’ — ‘whatever it takes’ was clear enough to steady the bond market and ease borrowing costs of eurozone governments.