Any other business

BMW’s Oxford retreat signals deep trouble for UK carmaking

Among British car factories, Nissan at Sunderland is the most productive and Jaguar Land Rover at Solihull probably the most advanced. As for industrial landmarks, the former British Leyland complex at Longbridge is reduced to a research and development facility for Chinese-owned MG; but ‘Plant Oxford’ at Cowley, the original home of Morris Motors now owned by BMW of Germany, still produces 1,000 Minis per day. And BMW’s decision to halt a £600 million project to build electric Minis there is, I fear, a moment of destiny for the whole UK auto industry. The truth is that the transition to electric cars has descended into chaos. Total UK car production in 2024 was at its lowest (in non-pandemic conditions) since 1954.
Brace for an outbreak of Trumpist investor activism

If the new Trump era has a theme, it’s one of quixotic disruption with random consequences. In that spirit, stand by for more interventions from activist shareholders seeking to electrify sluggish businesses while making fast bucks on the way through. The first episode over here was the attack by the New York investor Boaz Weinstein on seven London-listed investment trusts, in which he acquired stakes and forced shareholder votes to replace board members, with the aim of taking the trusts’ assets under the management of his own firm, Saba Capital. ‘Go home! You’re selfish and wasteful,’ shouted one headline after Weinstein was emphatically defeated in all seven polls.

Where have all the new businesses gone?

The Chancellor’s appeal to regulators last month for suggestions to boost growth was mocked as evidence that the government itself is hopelessly bereft of ideas. Might as well ask traffic wardens to devise urban regeneration schemes, we scoffed, or food safety inspectors to plan state banquets. But it made sense to the extent that smarter regulation really should have the potential to boost economic activity – and there are signs the message has got through. Bank of England governor Andrew Bailey speaks of using Brexit freedoms to shield smaller UK banks from ‘Basel rules’ that would require them to hold larger reserves.

Britain’s Trumpists should be careful what they wish for

When I visited Toronto with a UK delegation last winter, conversation focused on the issues of immigration, housing and inflation that were contributing to the unpopularity of Justin Trudeau, who finally announced his resignation as prime minister last month. The prospect of Donald Trump’s return to the White House was the slumbering python in the chandelier above the conference table: I sensed our hosts preferred not to think about how bad it might turn out to be. Well, now they know. In response to Trump’s declaration of 25 per cent tariffs on Canadian goods, plus 10 per cent on imported energy, Trudeau retorted with tariffs on many billions worth of US products.

I’m being driven mad by Microsoft Outlook

Call me a cynic, but I suspect this week’s headlines about a revival of Heathrow’s third runway plan amount to little more than a political game. Arguments for and against this project have been aired many times over, from a white paper in 2003 to the Davies Commission’s final report (in favour) in 2015. Much to the detriment of London’s status as a global city, the runway has stayed in the long grass – due to marginal-seat politics under the flight path as much as genuine environmental concern – while no satisfactory alternative at Gatwick or Stansted has ever advanced and the advent of the Elizabeth line is Heathrow’s only real improvement in living memory.

Would it be worth Trump buying Greenland?

London’s capital market needs a kick in the pants, as I write every week, and ‘activist investors’ are no bad thing if they provoke sharper corporate performance. The assault by the New York hedge funder Boaz Weinstein on seven UK investment trusts – demanding shareholder votes to replace directors with his own people and take the management of the trusts into his own firm, Saba Capital – looks like the kind of intervention that might bring positive change to the UK’s historic investment trust sector, which accounts for a third of FTSE 250 companies but according to critics offers lacklustre returns, with share prices too often stuck at discounts to the underlying value of trusts’ asset portfolios (NAV).

Rachel Reeves owes Brompton bikes an apology

I long to write less about Rachel Reeves and more about world-beating British businesses – such as Brompton, the folding bicycle maker whose fortunes I have followed since I bought the product and interviewed the founder-designer, Andrew Ritchie, 20 years ago. The latest Brompton news was that profits collapsed from £11 million in 2023 to breakeven for the year to March 2024 in the teeth of a post-pandemic demand slump; and that additional hiring has been put on hold after Labour’s NI increase added ‘hundreds of thousands of pounds’ of extra costs. A move from cramped west London premises to a new base at Ashford in Kent, with room for big increases in output and skilled jobs, had already been deferred to 2029.

My business predictions for 2025

Headed for ‘the worst of all worlds’ is not where any of us would wish to find ourselves at the start of the new year. But that was the phrase used by the CBI economist Alpesh Paleja to sum up the predictions of member businesses – of reduced hiring and output, rising prices and weak growth. Since that survey, a revision to zero of the official growth figure for the third quarter of 2024 and reports of depressed pre- and post-Christmas consumer spending have provoked even darker whispers of a return to recession. Whence cometh such pessimism? Has it bubbled out of the Tories’ black hole of fiscal shame? Can we blame the Bank of England and the Treasury ‘blob’? Or the rare alignment of planets that’s expected in three weeks’ time?

Negroni inflation is out of control

Forty years ago this Christmas I visited Hong Kong for the first time – a few days after the signing in Beijing of the Sino-British Joint Declaration that sealed the former colony’s transfer to mainland rule in 1997. It was a moment of apprehension, but at least the timetable had been set. And how lucky I was to have experienced that extraordinary outpost as it was then, in such contrast to what China’s masters have made it now. The Christmas Day service in St John’s Cathedral, overhead fans stirring the turbid air, was a poignant glimpse of Hong Kong’s past. Norman Foster’s Hongkong Bank building, the most expensive in the world at the time, was approaching completion as a symbol of commercial confidence in the future.

The marketing genius of Jaguar

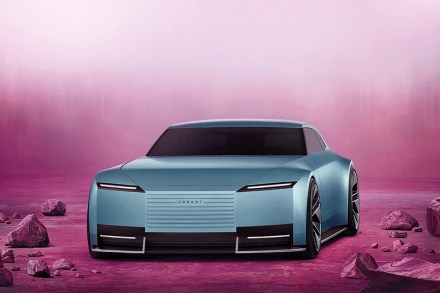
Woke it may be, but Jaguar’s ‘Copy Nothing’ video is a work of marketing genius. With its ungendered models, ungrammatical slogans (‘live vivid’, ‘delete ordinary’) and strange absence of cars, the 30-second ad has brought global attention to a brand that was dying for want of a new generation of customers, in an auto industry in turmoil over its stalled transition from carbon fuel to battery power. And a week later comes the reveal in Miami of the futuristic Type 00 electric concept car that the fuss was really about.

The dark side of Black Friday

How is it possible that we’re still reading headlines about the £4 billion fundraising from the Gulf that saved Barclays from a bailout in 2008? It’s not too sweeping to say that most of the financial world smelled something fishy in the undisclosed £322 million of advisory fees that were paid to Qatari investors – and that whiff never went away, despite the collapse of criminal charges against individuals at Barclays in 2019. The Financial Conduct Authority has called the behaviour of Barclays ‘reckless and lacking integrity’, while recognising that the bank ‘is a very different organisation today’.

What does the City really think of the Chancellor?

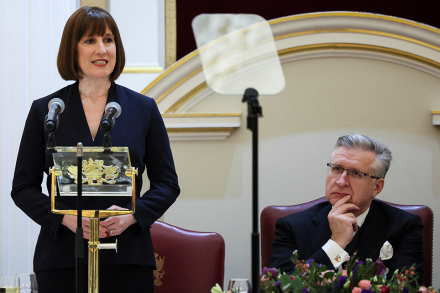
Regular invitations to Mansion House banquets petered out after I asked a shifty-looking waiter for a glass of champagne and he told me he was a deputy governor of the Bank of England. So I can’t report firsthand whether last week’s speech by Chancellor Rachel Reeves was greeted by assembled financiers with napkins on their heads or cries of ‘By George, I think she’s got it!’. What I can say is that – her text having been largely leaked beforehand – she was well upstaged by Governor Andrew Bailey’s unexpected attempt to reopen the Brexit debate; and that she seems to ‘get’ the City a lot better than she understands business owners, start-up entrepreneurs, shivering pensioners, aspirational parents and angry farmers. A low bar, but be thankful for small mercies.

Why Trump changed his tune on crypto

This column comes to you from Atlanta, Georgia, where but for one giant ‘Trump Stands Up For Families’ billboard and some Harris-Walz placards in the leafier suburbs, you would hardly know there had just been an election. I was hoping to report a whiff of teargas after a contested result, but no. Urban Atlanta voted for Harris but rural Georgia was so solid for Trump that nothing was left to argument. The chattering classes on the east and west coasts may be traumatised, but for plainer folks – with a sense of relief that no violent disruption kicked off – it’s back to daily life and business as usual. Or is that, I wondered, a false observation from conversations with my conference group here? ‘No, you’re right,’ a Washington economist told me over breakfast grits.

Is No. 10 coming for game shooting next?

I confess I was lunching at L’Escargot in Greek Street as Rachel Reeves delivered her Budget. My excuse was that I thought I already knew what was in it – but in reality the package was even more anti-business than I feared. My punishment was a risotto too glutinous to finish, but the Chancellor’s 76-minute sermon proved just as indigestible when I tuned in later. Like the wild mushrooms in my dish, the more pungent Budget measures had to be picked out of a blander mass – and I was roused from postprandial torpor by a call from a veteran entrepreneur, regularly quoted here under a variety of disguises, in a fury at one such small-print item.

Still hunting for a Trump trade? Gold may have further to rise

Anyone hunting for a ‘Trump trade’ at this late stage has probably missed the US election bus. If you bought gold as a traditional safe-haven asset back in February at £1,600 an ounce, you’d be a smug 33 per cent up by now – though my man in the bullion market tells me the rise is by no means all to do with presidential hopes and fears. There has also been big buying from China possibly linked to moves, with Russia and other unfriendly actors, towards ‘de-dollarisation’ of world trade using a partially gold-backed alternative currency. Which means there could be more upside ahead, my man says, and gold ETFs are still worth a look.

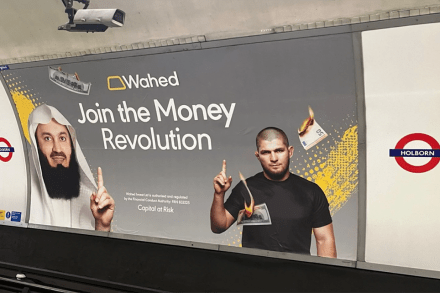
Wahed’s alarming Tube adverts

As the interminable Budget wait goes on, so does the trawl through the Chancellor’s bin bags. I refer to the old tabloid method of digging in celebrities’ dustbins for evidence of depravity or scandal; in Rachel Reeves’s case, that would mean piecing together shredded Treasury analyses on all the various tax wheezes floated since July. One curry-smeared paper no doubt addresses the pros and cons of an inheritance raid on ‘aristocrats and landowners’; beneath the Red Bull cans and pizza crusts, might there be another headed ‘Clawbacks on Enterprise Investment Scheme’? Not that there have been substantive rumours, mind you. But that’s rather the point: having had so many draft Budget items shot to pieces, she must be desperate to shield some last surprises.

In defence of eating out

Scheduling the Budget almost four months after their election victory would have counted as a monumental misjudgment for the Labour government were it not for all the other cock-ups that turned their first 100 days into a sitcom. Still, the extended period of speculation about which taxes Rachel Reeves is really planning to raise has done no good at all to her carefully groomed reputation as a ‘serious economist’ (to quote Mark Carney) who is somehow uniquely pro-business and pro-worker. On the contrary, there have even been suggestions that she could be about to unleash chaos on the financial markets akin to the Truss-Kwarteng fiasco of two years ago. But in essence it’s pretty obvious.

Where are all my after-dinner speaking gigs?

How excited are you to hear the Prime Minister talking tech with Eric Schmidt, an American billionaire who used to run Google? Me neither. But their on-stage conversation is billed as the highlight of the government’s International Investment Summit in London next week, designed to show the world the UK is ‘open for business’. What with Downing Street looking like Game of Thrones after the Red Wedding massacre, and both Angela Rayner’s Employment Rights Bill and Rachel Reeves’s tax-grab Budget looming, the timing of this summit could hardly be worse.

Goodbye to Old King Coal

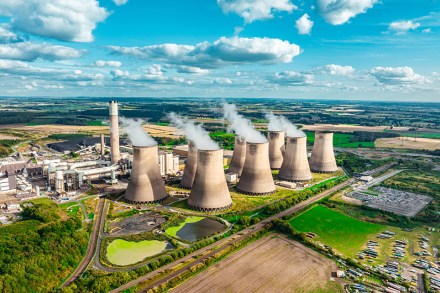
So farewell, Ratcliffe-on-Soar: the UK’s last coal-fired power station shut down on Monday, having burned five million tonnes of coal per year since it opened in 1968. Back then, 80 per cent of national power came from coal, our primary energy source since the 1880s; at the turn of this century there were still 25 coal plants in operation across the country. Now there are none – and 36 per cent of our power in the past year came from wind, solar and hydro with 7 per cent from biomass, compared with 24 per cent from natural gas and just 1 per cent from Ratcliffe’s coal. That’s a remarkable transition – but far from proof that we’ll have sufficient clean energy to keep the mid-century lights on.

The Murdochs’ next move: Rightmove

Next month’s Budget tax raids on capital have provoked a festival of creative doom-mongering on the fringes of Labour’s conference as well as in the columns of the business press. Most frequently voiced is the prediction that the 2,000 or so denizens of London’s private equity community who benefit from the ‘carried interest’ tax wheeze will pack their Louis Vuitton bags into their Chelsea tractors and form a convoy down the M20 towards continental tax havens.