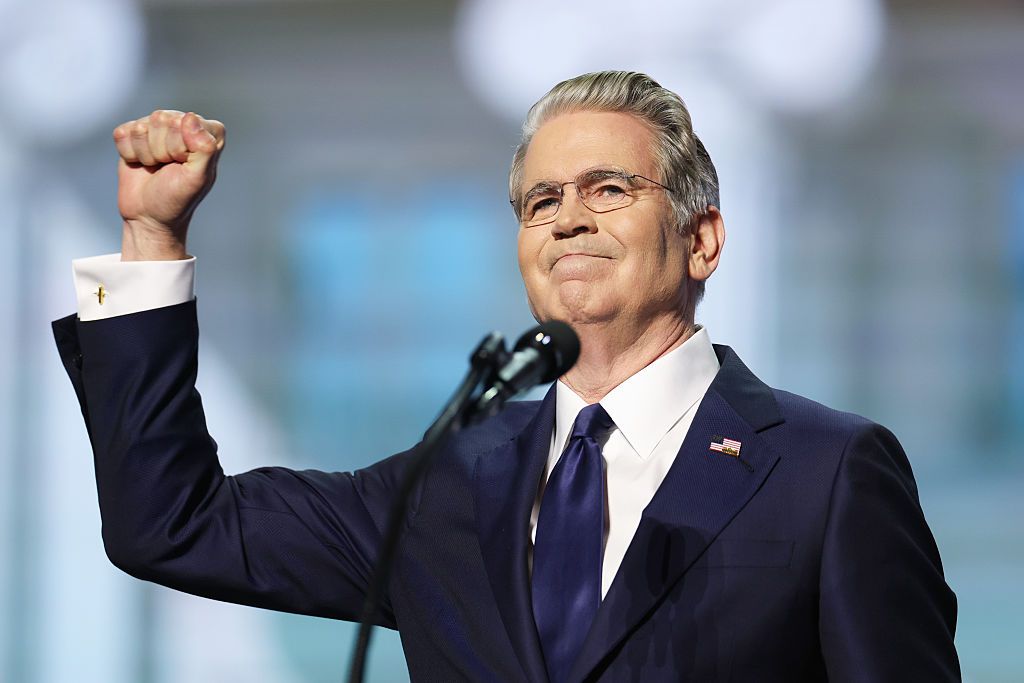
It was the kind of line that Robert De Niro would deliver perfectly in a gangster epic. “I am the house now,” the United States Treasury Secretary Scott Bessent declared confidently last week. “And you can bet against me if you want.” It was the most aggressive attempt yet by the most powerful financial official in the world to take on and tame the traders of Wall Street. With major interventions underway to control the yen-dollar exchange rate, and the yields on America’s $40 trillion national debt, Bessent’s message was clear. They will lose money if they dare to defy his will. Well, perhaps they will in the short term. With a background at the world’s most successful hedge fund, Bessent knows more about the market than most people. There is just one snag. He is also setting himself up to fail – and the only real question is when, not if, that happens.
For anyone who follows American high finance, it has been a dramatic few months. Last year, the Treasury stepped in to support the Argentinian peso, helping out that country’s radical free market President Javier Milei. Over the summer, the Treasury dramatically intervened to prop up the yen, in the first US purchase of the currency in almost three decades. Last month, amid turmoil in the bond markets that sent 30-year yields up to levels not seen since before the 2008 financial crisis, with 10-year yields not far behind, the Treasury intervened again, buying bonds to try and support prices and cap yields. On Thursday, the Treasury bought back $5.2 billion of 10- to 20-year debt, but yields rose regardless; the 30-year yield touched 5.37 percent, its highest since 2007. At the same time, Bessent ramped up the rhetoric, challenging traders to take on the Treasury Department, and sharply reminding them of the rules of the game. The house always wins was his message, and while you might be able to make a little money to start with, in the end the house always wins. Anyone who forgets that will end up losing everything. Last week, however, he qualified that bravado, saying he could not change the market’s “equilibrium price” and was only trying to slow things down.
He is getting himself into a fight that he can’t possibly win
Add them all up, and Bessent is emerging as the most interventionist Treasury Secretary for a generation or more. President Reagan finance chief James Baker, who with the Plaza and Louvre accords of the 1980s, attempted grand, multilateral currency strategies that reshaped exchange rates for years is probably the closest comparison, and before that Franklin Roosevelt’s long-serving Treasury Secretary Henry Morgenthau. But for at least the past quarter of a century, the markets have not seen anyone quite as forceful as Bessent. The Clinton, Bush and Obama administrations all accepted that it was the markets that dictated terms to the government, not the other way around, and there was not much that could be done to change that.
In fairness, if you wanted a Treasury Secretary who could take on the traders, Bessent would be the best man you could pick. He is not just a former hedge fund manager, he is a former Soros hedge fund manager. He was a key player in the $1 billion attack on the pound in the early 1990s, and in dozens of trades since then. Big macro currency plays are what Bessent does best, and he has come out on the winning side more often than not.
The trouble is, Bessent is getting himself into a fight that he can’t possibly win. His interventions may have some initial success, and certainly more than many of his fiercer critics imagine. The Argentine trade turned out to be profitable. The yen has remained volatile since the intervention, but the collapse has been stopped at least for now, but today remains near a seven-month high, up around 4 percent this month. The yield on 10-year US Treasuries reached 4.9 percent on Friday, barely below the crucial 5 percent barrier. Many of his critics are suffering from such an extreme case of Trump Derangement Syndrome that they automatically assume anything the administration does will end in immediate disaster. It won’t necessarily work out like that. Bessent is smart, he knows how the traders operate, he knows where the pain threshold is on the profit and loss account, and he has all the financial firepower of the American state behind him. With Kevin Warsh, another Trump ally, installed at the Federal Reserve, he may well be able to co-ordinate his interventions with the world’s most powerful central bank. That is a lot of muscle.
Even so, it is not addressing the real issue. The budget deficit has soared out of control, running at more than 5 percent of GDP even at a time when the economy is doing relatively well. Figures released on Friday showed that it had reached $1.97 trillion in the first 11 months of the fiscal year, already exceeding the entire 2025 deficit. The total debt has hit 122 percent of output, although there is no major crisis to deal with, and it keeps on rising all the time.
With the Artificial Intelligence boom demanding vast investment in data centres, capital is scarce once again, and, not very surprisingly, you have to pay more for it. And on Sunday, Trump insisted that America could “easily” afford his proposal to send $5,000 to every adult if Republicans retain Congress – a pledge that would require congressional approval and cost roughly $1.2 trillion. Bessent can play all the tricks he learned running one of the world’s most ruthlessly successful hedge funds. He can try and bully the markets into submission, or find a whole series of clever ways of stopping yields from running out of control. It is not going to work.
Until there is a President who is willing to raise taxes modestly and hold spending until the deficit starts to come under control, and, even better, who sets out a two-term plan to balance the books, bond yields are going to keep on rising. You can’t fight the markets forever. In reality, the government debt market is not a casino, and Bessent is not “the house.” Sooner or later, his hubristic remarks will come back to bite him. It is just a question of when that happens.


Comments