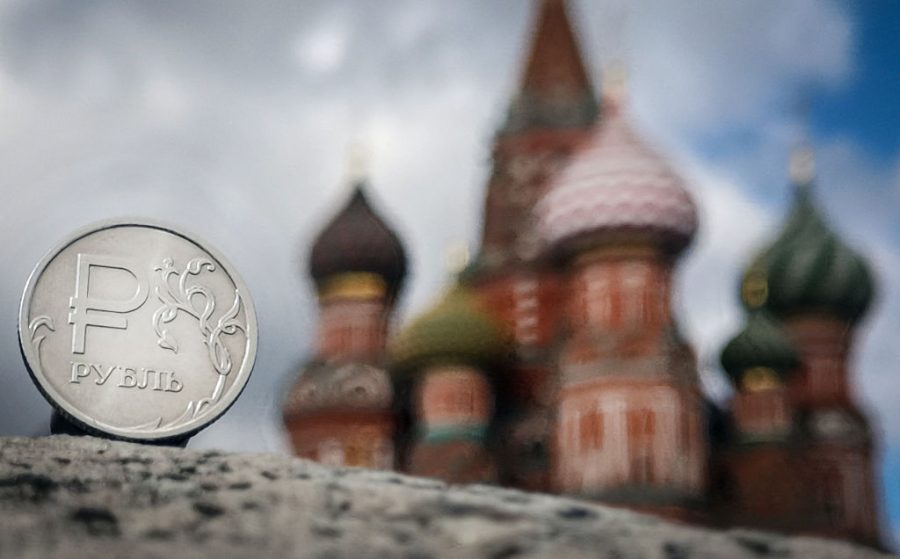
For several years already, every fall, Russia’s finance ministry has performed the same ritual. It unveils a budget that looks sober, even responsible, with a shrinking deficit and falling inflation. Every year, it is ignored by reality. The budget for 2027, outlined at the end of last week, is no exception.
The headline promise is a deficit of 2.2 percent of GDP next year, about 5.5 trillion roubles ($65 billion), down from roughly 3 percent expected this year. Revenues are to rise by 7.5 percent, which after inflation is barely 1 percent. Spending will grow by less than 6 percent, which after inflation is a cut of about 1 percent. For the first time since the invasion of Ukraine, the government even plans to start refilling the National Welfare Fund, the country’s rainy-day savings. Two-thirds of that fund has already been spent keeping Russia’s war economy afloat.
Vladimir Putin is mortgaging Russia’s future to pay for his present geopolitical aims
It all sounds admirably prudent – and it would be if anyone believed it. The finance ministry’s plan assumes that the economy will grow by 1.4 percent next year. The central bank expects growth of 1.2 percent, and the OECD a mere 0.6 percent. It assumes inflation will fall from 6.8 percent at the end of this year to the 4 percent target by the end of 2027. Ordinary Russians, who see the prices in the shops every day, disagree. They expect prices to rise by 14.2 percent over the next year and reckon those they already pay are climbing at 15.1 percent. Only the forecast for the price of oil is cautious – but the rule that once tied spending to oil revenues has been suspended until 2029, allowing the government to loosen its frugality.
Two things will decide how this budget actually turns out, and the Kremlin prefers to discuss neither. The first is how much the war in Ukraine really costs. The second is whether the government intends to stick to its own numbers.
On the first point, Anton Siluanov, the finance minister, has at least been honest about the government’s priorities. Defense comes first, and so do the social payments that keep the population quiet: weapons, factory upgrades, soldiers’ pay, money for their families. How much and on what, exactly, nobody outside a small circle knows, since (as in previous years) a large share of this spending will again be classified. These published figures are best read as the opening bid in a negotiation between the finance ministry and the military’s generals. The generals rarely lose to the technocrats.
On whether the government intends to stick to its own numbers, the record speaks for itself. Moscow has not hit a single deficit target since the invasion. Last year it promised a gap of 0.5 percent of GDP and ended with 2.6 percent. This year’s target of 1.6 percent had been blown by February and is expected to be about 3 percent by the end of the year.
A year ago, the ministry announced it would trim military spending in 2026; it will almost certainly end the year spending more. A plan to cut “non-sensitive” spending by a tenth was shelved when the war in Iran sent oil soaring. Even that windfall largely evaporated, eaten by a strong rouble and by payments to oil companies to keep petrol cheap at home.
So who is this budget really for? First and foremost, the Russian central bank. Interest rates remain painfully high, and the Kremlin wants them lower. The central bank has said it needs fiscal restraint first, and the budget offers exactly that on paper. That would give the Bank of Russia room to resume cutting rates. But if the arithmetic goes awry, as it has in the past, rates will stay high for longer.
Meanwhile, somebody has to pay. Having already raised income tax, corporate tax and VAT, the government is now reaching into less obvious pockets. Income from savings and investments will be taxed at the higher progressive rates, with war veterans exempt, naturally. Miners and fertilizer producers, among the few still earning decent money abroad, face a one-off levy on windfall profits, which is hardly an encouragement to invest. Investors from “unfriendly” countries will see the tax on their frozen dividends more than double. Online shopping from abroad will cost more, as well as tobacco and booze, while utility bills will rise faster than planned. Still, there are doubts that the deficit and the debt will stay within the finance ministry’s parameters.
To be honest, none of this looks bad by Western standards. A deficit of around 2 percent of GDP would be the envy of Washington, London or Paris. Russia’s public debt is under a fifth of GDP. America’s is about 126 percent, France’s about 118 percent and Britain’s around 100 percent. Japan’s is above 200 percent, and the bond markets have not yet fled.
The difference lies in who lends, and what for. Western governments borrow from the whole world, but Russia, shut out of international markets, can borrow only from its own banks – and at double-digit rates. The money does not go into roads, factories, schools or hospitals. It goes into shells and drones, which produce nothing anyone can buy. Thus it doesn’t raise productivity or the potential of the economy. More money chasing the same goods means higher prices. Higher prices keep interest rates high. High rates choke the civilian businesses that cannot count on state orders and subsidies, while the defense sector carries on regardless. Each turn of that wheel widens the gap between the two economies, the military and the civilian.
Inflation is the real tax paying for this war. It fell first on the urban middle class, the people with savings to erode, who are now also the main target of the new tax on investment income. Now, however, it is spreading to everyone. Lavish war spending has pushed real incomes up by almost 7 percent annually on average in the past three years, more than twice the pace of economic growth. That party is over. Real incomes are expected to grow by just 1 percent this year and 1.4 percent next. The gap between those who profit from the war and those who merely pay for it will keep growing.
This proposed fiscal tightening doesn’t solve the problems the Russian government is facing. It just pushes them into another year, in the hope that the war ends, oil rallies, or Washington softens before the bill falls due. Each such year leaves Russia with thinner savings, dearer debt, heavier taxes and fewer ways to absorb the next shock. If the war escalates this winter, as seems likely, these numbers will be torn up by spring, as they were in the past two years.
The Russian economy is not collapsing, of course, but it’s slowly rotting. Vladimir Putin is mortgaging Russia’s future to pay for his present geopolitical aims. The new budget does not change that arrangement – it simply raises the country’s monthly payments.

Comments