The shift to the right across South America has been stopped. One of President Trump’s key regional allies has been defeated. The global left, and most of the centre, has been celebrating the victory of President Lula over Flávio Bolsonaro in a closely fought election this weekend. There is just one problem. As the brutal sell-off of financial assets demonstrated, Brazil has also voted for economic chaos. That rarely ends well.
The election may tip Brazil into a full-scale crisis
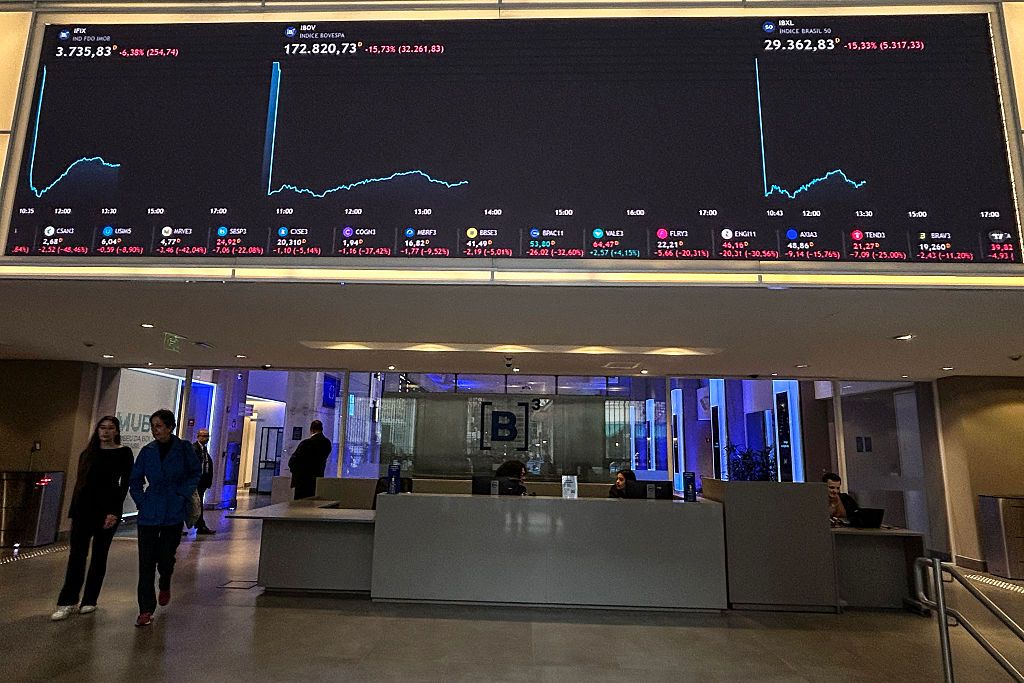
While the left were toasting victory on Monday morning, investors were furiously dumping Brazilian equities and, more importantly, debt. On Monday the Bovespa – Brazil’s main stock market index – fell by over 15 percent. The real lost as much as a tenth of its value, its worst trading day since 1999. Meanwhile, the ten-year local bond yield jumped from 13 percent to more than 15 percent in a single session. Amid the rout, the country cancelled two debt auctions. It was ugly, and shows little sign of calming down any time soon.
In reality, the sell-off made perfect sense. Investors had anticipated a Bolsonaro victory, and were expecting lower taxes, controls on spending and pro-business reforms once their man took power. They had positioned their books accordingly, confidently expecting a post-election rally. After all, on the night before the election, the prediction markets, which are increasingly taken as gospel on Wall Street, gave the right an 80 percent chance of victory. As that prospect of that disappeared, they reversed all those trades as quickly as possible.
Additionally, the result was so close, and there have been so many allegations of judicial interference, that the political system is likely to be deadlocked for years. Uncertainty on that scale is never good for the economy.
Lula, as so often in the past, campaigned on massive bribes to the electorate. In the run-up to the vote, his government rolled out a package of benefits worth between 180 billion and 220 billion reals, depending on how it is counted. He campaigned on a very traditional platform of left populism, promising to relaunch the Bolsa Família – a cash transfer which is now paid to more than twenty million low-income families – along with green industrial policies and a bigger role for state-owned enterprises and banks. Perhaps because he didn’t expect to win, little attention was given to how Brazil would pay for it all. In the background, however, debt has already risen by more than ten points of GDP over Lula’s current term, and it is now heading towards 90 percent.
Finally, and probably worst of all, those expensive election promises were made at a time when bond yields are rising right across the world. France is already in trouble with the markets, and Britain is teetering on the edge. Brazil picked the worst possible moment to get into a fight with the bond vigilantes. It has already become a lot more expensive to borrow money, and that is for countries which, to put it politely, have a slightly better record of paying back their debts in full than Brazil.
The election may well tip Brazil into a full-scale crisis. In fairness, most of its debts are now in the real, instead of in dollars, which makes it easier to manage. And growth has been strong over the last five years, with an average annual expansion of 3.5 percent, mainly on the back of booming commodity exports. However, there may well be fresh tariffs from the Trump White House, and given that the United States is Brazil’s second largest trade partner (China has overtaken it in first place) and foreign investment is likely to be on hold at least for now, it is hard to see the economy growing significantly this year.
Lula and his supporters may be celebrating for now. But Brazil has defaulted on its debts between seven and nine times in its history, depending on how you count then, and there is no reason why a tenth should not be added to the list. The markets have already delivered their verdict on the re-elected government – and it is going to prove a very tough few years ahead.

Comments